
Table of Contents
TL;DR
Frugality helps you pay less for the things you buy. Minimalism goes one step further by questioning how many things you need to own at all. Fewer vehicles, upgrades, stored items and financed purchases can mean less depreciation, maintenance, insurance and debt. The goal is not an empty house. It is a balance sheet built around assets that support your future.
Frugality vs. Minimalism: The Net Worth Difference
Frugality asks, “How can I spend less on this purchase?”
Minimalism asks, “Do I need this purchase in the first place?”
Both can improve cash flow. A frugal shopper may buy furniture on sale, choose a lower-cost car or avoid full-price electronics. A minimalist may keep the furniture already owned, live with one reliable car instead of two or stop buying upgrades that add little value.
There is an important balance-sheet correction: possessions are not liabilities simply because they lose value. A paid-off car, phone or piece of furniture is still an asset at its current resale value. It becomes part of the liability side only when debt is attached.
The net worth advantage of minimalism comes from reducing exposure to depreciating assets and the recurring costs that follow them. Fewer financed purchases mean fewer debts. Fewer excess possessions can mean lower storage, maintenance and replacement costs. The money kept can be directed toward savings, investing or paying down liabilities.
How Possessions Reduce Net Worth
Depreciation Is a Real Cost
Many purchases lose value soon after they are made. That decline may not appear as a bill, but it appears in net worth when you calculate the item at its current resale value.
Vehicles are one of the clearest examples. AAA’s 2025 Your Driving Costs study reports that depreciation was the largest average cost of new-vehicle ownership in its analysis, at $4,334 per year across the study vehicles.
Take a simple illustration. You buy a new car for $45,000. Three years later, its resale value is $27,000. Your asset value has fallen by $18,000. If you also financed the car, interest and any remaining loan balance further affect your financial position.
Electronics and furniture often follow the same pattern. A household spending $3,000 each year replacing phones, televisions, tablets and other technology may own items worth far less on the resale market later. A $5,000 furniture upgrade may be useful and attractive, but secondhand value can be only a fraction of the purchase price.
This does not make every purchase a mistake. A car may be necessary for work. Furniture makes a home usable. The problem is repeatedly buying more value loss than your income can comfortably absorb.
The Costs That Continue After the Purchase
Depreciation is only the first part of ownership cost.
A second vehicle can add insurance, registration, fuel, repairs and parking. A boat, recreational vehicle or vacation property can create maintenance and storage expenses even during periods of limited use. Excess belongings may lead to renting extra storage space rather than deciding what should be kept.
Storage alone can become a quiet drain. SpareFoot reported that a typical 10-by-10-foot non-climate-controlled storage unit averaged $119 per month entering 2026. That is $1,428 per year spent to hold possessions that may themselves be losing value.
Suppose someone sells unneeded stored belongings for $2,000, ends a $119 monthly storage rental and invests both amounts instead. At a hypothetical 7% annual return, the initial $2,000 plus $119 invested monthly could grow to approximately $24,600 after 10 years.
That projected result is not guaranteed. Investments carry risk. But the example shows what excess ownership can cost: not only the storage bill, but also the future value of money that never had the chance to build assets.
The Minimalist Net Worth Audit
Minimalism becomes financially useful when it is specific. Do not begin by throwing away inexpensive items that make everyday life easier. Start with possessions that carry meaningful value or ongoing expense.
List your vehicles, costly electronics, recreational items, stored furniture, collections and any financed personal purchases. For each item, write down its realistic current resale value, any loan balance attached to it and what it costs annually through insurance, storage, subscriptions, maintenance or repairs.
Then ask:
- Do I use this enough to justify its annual cost?
- Is debt attached to an item that is losing value?
- Could selling it remove a monthly cost or loan payment?
- Would using the proceeds for debt reduction or investing strengthen my balance sheet?
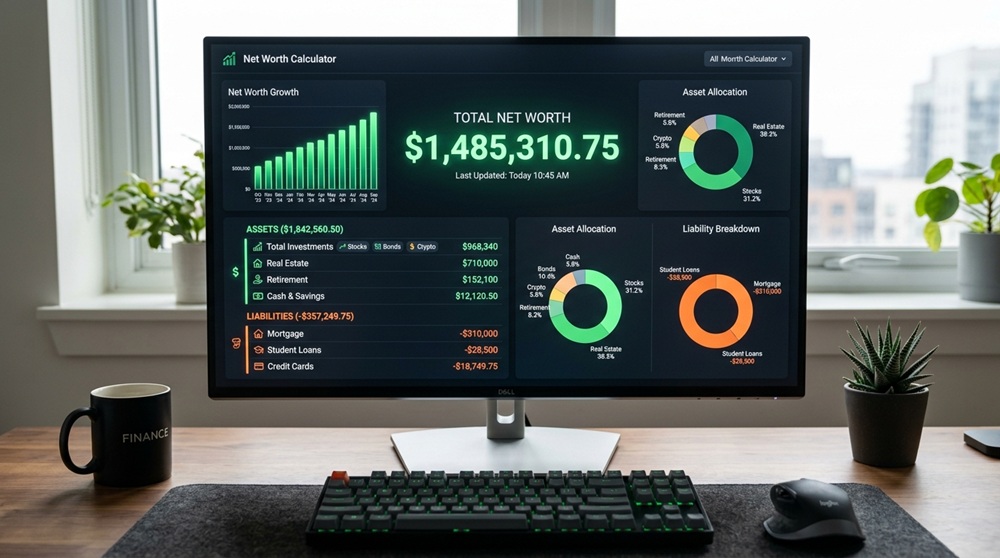
A tool that lets you see your full asset picture helps you enter current vehicle value, cash, investments and outstanding liabilities in one place. The purpose is not to pretend every possession is worthless. It is to see how much of your net worth is held in assets that decline in value versus assets that can support long-term financial progress.
The Counterintuitive Truth About Quality
Minimalism does not always mean buying the cheapest option. A low-cost item that needs frequent replacement can create more spending than one durable purchase that lasts years.
The stronger rule is to own fewer items intentionally. A well-made coat worn regularly for years may make more sense than repeated purchases of clothing rarely used. A reliable vehicle kept for a long period may be financially stronger than frequently upgrading to newer models.
Quality does not guarantee resale value, and an expensive label does not make a purchase wise. The question is still practical: will this item be used enough, last long enough and fit the budget without reducing higher-priority goals?
Minimalism works when purchases become deliberate rather than automatic.
What Minimalism Creates Beyond Lower Spending
A simpler financial life can also be easier to manage. Fewer financed items mean fewer payment dates. Fewer unnecessary belongings mean fewer repair, storage and replacement decisions. Lower recurring costs can create more flexibility when income changes or an unexpected expense arrives.
That flexibility has value. It may allow you to increase retirement contributions, keep an emergency fund intact or avoid using credit when life becomes expensive.
For more practical guidance on tracking assets, liabilities and financial progress, visit NetlyWorth.
Own Less of What Loses Value and Build More of What Lasts
Frugality helps you reduce the price of purchases. Minimalism helps you reduce the number of purchases competing with your future.
You do not need to sell everything or avoid useful comforts. You need to recognize which possessions are draining cash, losing value and keeping money away from stronger assets. Audit what you own, keep what serves your life and redirect avoidable ownership costs toward the balance sheet you want to build.